Zero annual fee. Zero forex markup. Unlimited domestic lounge access. 20 percent back on travel bookings through the app. On paper, the Federal Scapia Credit Card looks like someone built the ideal travel card for budget conscious Indians and forgot to charge for it. It’s genuinely strong, with one quirk that trips people up: the rewards only go back into travel. No cash, no statement credit, nothing outside the Scapia app.
That one limit decides who this card suits and who it quietly frustrates. It’s one of the most distinctive entries among travel credit cards and lifetime free credit cards: it gives more than most free cards on travel earning, then keeps control of how you spend it.
What the Scapia Credit Card Actually Gives You
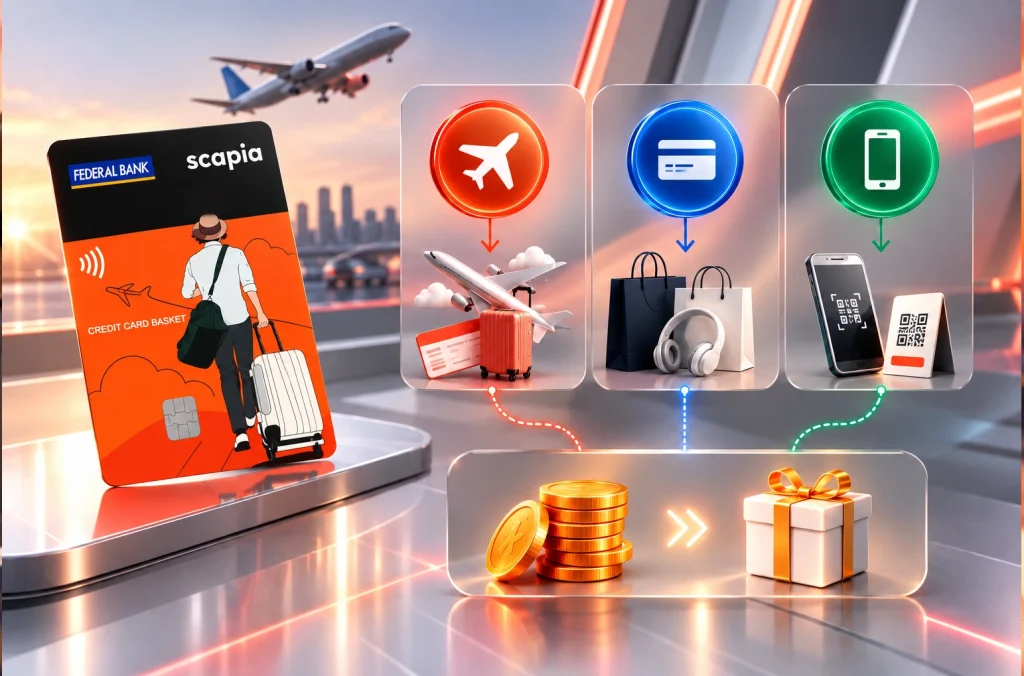
Scapia credit card benefits start with two headline features: zero forex markup abroad, and unlimited domestic lounge access once you spend Rs. 20,000 a month.
Zero forex markup means international transactions go through at the standard Visa exchange rate with nothing added. Most Indian cards charge 1.5 to 3.5 percent, so on Rs. 1,00,000 spent across a two week trip you save Rs. 1,500 to Rs. 3,500 that most travellers pay without noticing.
The lounge rule changed in February 2026, when Scapia doubled the monthly threshold from Rs. 10,000 to Rs. 20,000. Spend Rs. 20,000 combined across Visa and RuPay in a calendar month and the whole next month unlocks, with no per visit cap. Miss it and access disappears for that month, however often you fly. Paid cards charge Rs. 2,500 to Rs. 5,000 a year for this, so it’s a great deal if you hit the number monthly, and shaky if your spending swings.
How Scapia Coin Rewards Work
Scapia credit card rewards come as Scapia Coins in three tiers:
- 20 percent on travel bookings in the app: flights, hotels, buses, trains, visa applications and experiences
- 10 percent on other eligible online and offline Visa spends
- 5 percent on UPI and RuPay spends above Rs. 500 through Scapia Pay
Five Coins equal Re. 1. A Rs. 10,000 flight earns 2,000 Coins worth Rs. 400, and Rs. 5,000 of general spend earns 500 Coins worth Rs. 100. That’s an effective 4 percent on travel and 2 percent elsewhere, both competitive for a zero fee card.
Redemption is where it gets tricky. Coins work only for travel bookings inside the app.
| Redemption Option | Available |
| Travel bookings inside the app | Yes |
| Statement credit | No |
| Vouchers | No |
| Catalogue | No |
| Airline transfers | No |
Travel often and book through Scapia, and the loop closes neatly. Travel occasionally or prefer airline sites, hotel apps and OTAs, and the coins pile up while the rewards stay theoretical. The Federal Bank credit cards partnership brings backing from one of India’s more reliable mid sized private banks, but the app is where the value lives or dies. Curious what you’d earn? CCB’s rewards calculator gives you the rupee figure.
Airport Privileges Most People Miss
| Factors | Domestic Departures | International Departures |
| Condition | Meet the Rs. 20,000 monthly threshold | Book a flight of Rs. 40,000 or more through the app |
| Earn Back | Up to Rs. 1,000 as Coins | Up to Rs. 2,000 in Coins |
| Eligible Spends | Airport dining, shopping and spa spends | Duty free, dining or brand outlets |
| Where | Every domestic airport | The Indian international terminal |
| Effective Return | Nil | Effectively 5 percent back on airport retail and dining |
The Dual Card Advantage: Visa and RuPay
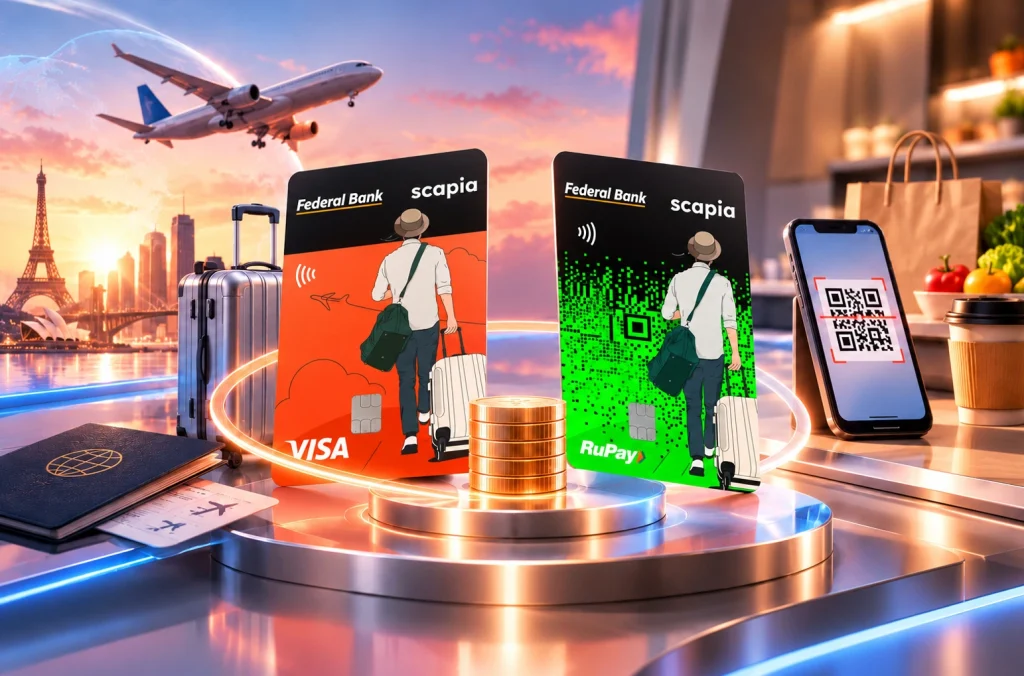
Apply and you get both a Visa and a RuPay card on one account, sharing a single credit limit.
Apply and you get both a Visa and a RuPay card on one account, sharing a single credit limit.
| Visa | RuPay | |
| Used For | International and general spends | Links to UPI through Scapia Pay for Scan and Pay at offline merchants |
| Key Benefit | Zero forex markup applies | 5 percent Coins on UPI transactions of Rs. 500 and above |
Visa and Mastercard cards can’t be linked to UPI for merchant payments, so most credit cards can’t offer this. NPCI explains the basics in its RuPay credit card on UPI FAQs.
If you pay autos, local vendors and neighbourhood stores through UPI daily, Rs. 10,000 a month earns 500 Coins worth Rs. 100, or Rs. 1,200 a year from spends that would otherwise earn nothing.
If you pay autos, local vendors and neighbourhood stores through UPI daily, Rs. 10,000 a month earns 500 Coins worth Rs. 100, or Rs. 1,200 a year from spends that would otherwise earn nothing.
Scapia Card Works Best For
It’s built for one kind of traveller: someone who books domestic flights and hotels at least once every two months, uses Scapia as their main booking app, spends Rs. 20,000 or more monthly on the card, and travels abroad at least once a year. For them it’s one of the best zero fee propositions in India.
It works less well if you book through airline apps, hotel loyalty portals or MakeMyTrip. Booking through Scapia means giving up airline miles, hotel points and OTA cashback in exchange for Coins, and whether that’s worth it depends on what you already use.
Want to compare with paid cards that offer airline transfer partners and uncapped redemption? Our travel credit cards comparison covers zero fee to premium.
The Bottom Line
The trade off is simple. You get an exceptional zero fee travel card that earns well and charges nothing on forex. In return, every rupee of rewards stays inside the Scapia ecosystem until you book another trip.
If travel is already part of your life and you’re happy booking in the app, this card funds itself. If travel is occasional or you’re loyal to airline and hotel programmes, the balance will outgrow your ability to use it.
Worth holding? For frequent domestic travellers and anyone making one or two international trips a year, yes. As your only travel card? That depends on whether Scapia becomes how you book, or stays one more app you forgot to open. For confirmed current terms, see Federal Bank’s official Scapia card listing, and Paisabazaar’s Scapia review offers an independent view.
Frequently Asked Questions
Not really. Coins redeem only for travel bookings in the app, so if you travel less than once every two to three months they’ll pile up faster than you can use them.
Yes, but only on the Visa variant, at the standard Visa exchange rate. International transactions don’t earn Scapia Coins.
You won’t have access the following month. It resets monthly on the previous month’s combined Visa and RuPay spend, so meeting the threshold again brings it back.
Yes. Scapia allows 100 percent coin redemption against eligible bookings, so you can use all your coins in one transaction.
Yes, as a complement. The zero forex markup and RuPay UPI earning add value where premium cards often underperform, and it costs nothing to hold.