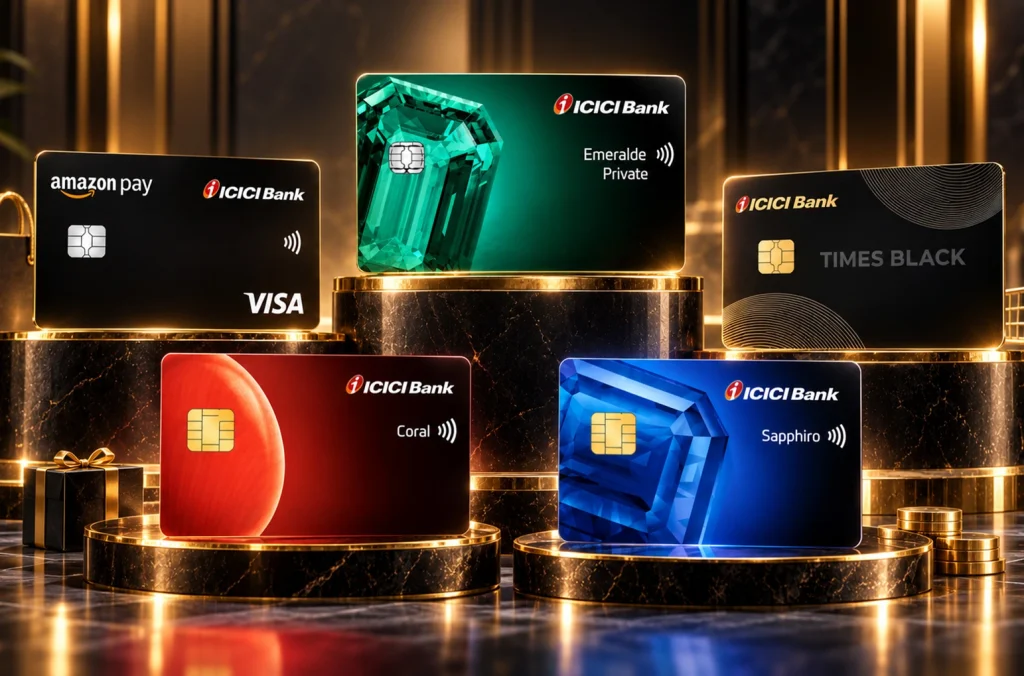
ICICI credit card lineup is honestly all over the map, in a good way. There’s a lifetime free card quietly earning 5% on your Amazon orders, and then there’s a metal card at the other end returning 36% on hotel bookings if you know where to click. In between sits a whole stretch of cards, each built for a different kind of spender, and picking the wrong one usually means you’re leaving real money on the table every month without realizing it.
The real question was never “which ICICI credit card is best.” It’s which one actually earns the most on whatever you’re already spending. Most people just guess at this. The ICICI savings calculator (also known as the ICICI reward point calculator) skips the guessing; you plug in your monthly spend by category, and it tells you, in rupees, what each card would actually return.
Two ICICI Reward Systems, and They’re Nothing Alike
Here’s something that trips a lot of people up: ICICI actually runs two separate reward systems, and they look similar on the surface but pay out very differently.
Most cards run on ICICI Bank’s standard reward points system. Points redeem for roughly ₹0.25 to ₹0.40 each if you’re cashing out, or up to ₹1 if you go through the credit card rewards catalog instead. The typical earn rate is 2 points per ₹100 spent, which works out to about 0.5% back in cashback. Not nothing, but not exciting either.
Then there’s iShop, which kicks in on premium cards like the Emeralde Private Metal and Times Black. On iShop, 1 point is worth a flat ₹1. So a card earning 3% normally suddenly becomes an 18% card on flights and a 36% card on hotels, purely because you booked through the ICICI iShop portal instead of going direct. That gap is honestly the single most important thing to understand before you pick a card based on its advertised rate.
The ICICI savings calculator already accounts for both systems, so it applies the right rate per card and category automatically and just hands you the annual number.
How the ICICI Cards Stack Up
| Card | Annual Fee | Base Rate | iShop Flights | iShop Hotels | Best For |
| Amazon Pay ICICI | Free for life | 5% cashback (Prime) | N/A | N/A | Amazon-heavy spenders |
| ICICI Coral | ₹500 | 0.50% | 3% | 6% | Entry-level everyday use |
| ICICI Sapphiro | ₹3,500 | 0.50% | 3% | 6% | Lifestyle and dining |
| ICICI Emeralde | ₹12,000 | 1% | 6% | 12% | Mid-premium travel |
| ICICI Times Black | ₹20,000 | 2.50% | 12% | 24% | Premium lifestyle & travel |
| Emeralde Private Metal | ₹20,000 | 3% | 18% | 36% | Heavy spenders, travel maximisers |
The Easy Pick: Amazon Pay ICICI
If you shop on Amazon regularly and already have Prime, this one’s barely a decision. 5% cashback on everything you buy there, dropped straight into your Amazon Pay balance, zero annual fee, no cap anyone’s mentioned, no portal to remember.
Without Prime, it drops to 3% on Amazon and 1% everywhere else, but even then, since the card costs nothing to hold, every rupee you earn is pure upside. It doesn’t touch iShop at all, so its whole value lives inside the Amazon ecosystem. If Amazon eats up 40 to 60% of what you spend online each month, this card earns its spot in your wallet no matter what else you’re carrying.
The Middle Ground: ICICI Sapphiro
Sapphiro earns 2 points per ₹100 domestically and 4 internationally, which is a pretty unremarkable 0.5% on paper. But run bookings through iShop, and it jumps to 3% on flights and 6% on hotels.
If you’re spending somewhere between ₹15,000 and ₹25,000 a month on everyday stuff plus the occasional trip, that ₹3,500 annual fee can be clawed back from a single hotel booking made the iShop way. Add in lounge access, golf perks, and dining discounts, and it becomes a genuinely better card than its base rate would suggest on its own.
The Big One: Emeralde Private Metal
This is where ICICI’s whole reward story peaks. At ₹20,000 a year, it earns 6 points per ₹200 at base, which comes out to 3% through iShop. Fine, but nothing special yet.
What actually makes it worth the fee is the multiplier once you’re booking through the portal. 18% on flights. 36% on hotels. 18% on gift vouchers too. These numbers are genuinely among the best you’ll find on any Indian credit card in these categories. There’s a cap: 18,000 iShop points a month, 10,000 a day, which tops out at ₹18,000 in credit card rewards value monthly. But for someone who travels often and routes real spend through iShop, the annual fee pays for itself with one international hotel booking above ₹56,000.
Why the Booking Link Matters More Than You’d Think
Here’s a concrete example. Book a ₹10,000 flight directly on the airline’s own site with an Emerald Private Metal, and you’ll earn 300 points, worth ₹300 at the base 3% rate. Book that exact same flight through iShop instead, and you’d earn 1,800 points, worth ₹1,800 at 18%. Same flight. Same card. ₹1,500 of the difference just from which tab you booked it in. That’s really why building the iShop habit pays off so consistently. If you’re curious how this stacks up against what HDFC’s SmartBuy offers in similar categories, the credit card rewards comparison lays both out side by side.
Let the Calculator Do the Math
The table above is a good starting point, but it’s still theoretical. The ICICI Savings Calculator tells you what a card earns on your actual spending, and that difference matters more than people expect. Someone spending ₹8,000 on Amazon, ₹5,000 on dining, and ₹15,000 on travel will get a totally different recommendation than someone spending ₹40,000 on flights and ₹20,000 on hotels every month, even if they’re both staring at the same comparison table. Plug in your numbers, pick the cards you’re torn between, and see what each one actually nets you after the fee.
Matching the Card to You
Mostly shop on Amazon; don’t want to pay a fee: Amazon Pay ICICI. Free forever, 5% uncapped if you’ve got Prime.
Spend moderately, want some lifestyle perks and occasional travel value: ICICI Sapphiro. One iShop hotel booking usually covers the fee.
Travel often, spend ₹5 lakh or more a year: Emeralde Private Metal. The iShop multipliers make the fee worth it if you’re actually routing spend through the portal.
Just getting started: ICICI Coral. Low fee, base-tier iShop access, and an easy entry point.
Still not sure where you land? The ICICI bank calculator sorts that out in under two minutes using your own numbers instead of a generic answer.
Frequently Asked Questions
Emerald Private Metal hands down, up to 36% on hotels and 18% on flights through iShop. If you’d rather skip the portal altogether, Amazon Pay ICICI gives Prime members a flat 5% on Amazon with no cap.
Just use the ICICI Savings Calculator. Enter what you spend monthly by category, and it shows you the annual value for each card based on your actual habits.
Cash it out normally, and you’re looking at ₹0.25 to ₹0.40 a point. Go through iShop or the voucher catalog instead, and it can be worth up to ₹1. Always check which route you’re using before assuming a fixed value.
For premium cardholders, yes, genuinely. It turns a plain 3% card into 18% on flights and 36% on hotels. One extra click to book through the portal, but the payoff makes it worth building into a habit.
Open iMobile Pay or your internet banking and head to the credit card rewards tab under the credit card section. ICICI’s own rewards redemption portal also shows the current catalog and what each point is worth.