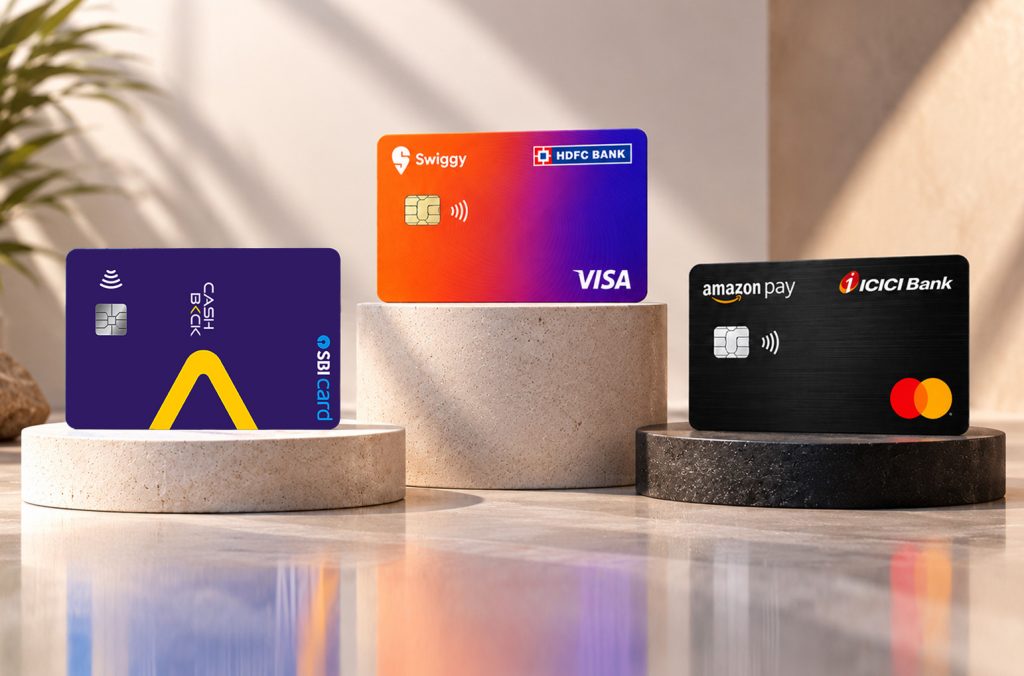
Three cards. Three issuers. All claiming to be the best cashback credit card for everyday spending in India. The SBI Cashback Credit Card, the HDFC Swiggy BLCK Credit Card, and the Amazon Pay ICICI Credit Card each have a loyal following, a genuinely strong use case, and a blind spot that its marketing page quietly glosses over.
The honest answer is that none of these cards is universally better than the other two. The one that puts the most money back in your pocket depends entirely on where your monthly spending actually goes. Worth knowing before diving in: SBI, HDFC, and ICICI each run card portfolios that go well beyond these three products.
The SBI credit card range sits at the more straightforward end of its issuer’s lineup, the HDFC Swiggy BLCK is one of the newer co-branded additions to what is already India’s largest credit card portfolio, and the Amazon Pay ICICI card has quietly become one of the most held lifetime free cards in the country. Understanding where each one fits within its issuer’s broader ecosystem tells you a lot about who it was really built for.
The Cards Comparison at a Glance
Before getting into the nuance, here is where each card stands on the fundamentals.
| Feature | SBI Cashback Card | HDFC Swiggy BLCK | Amazon Pay ICICI |
| Annual fee | Rs. 999 + GST | Rs. 1,000 + GST | Lifetime free |
| Fee waiver | Spend Rs. 2 lakh annually | No waiver | No waiver needed |
| Top cashback rate | 5% on online spends | 10% on Swiggy | 5% on Amazon (Prime) |
| Categories covered | All online merchants | Swiggy ecosystem only | Amazon, partner brands |
| Offline cashback | 1% on offline spends | 1% on other spends | 1% on offline spends |
| Monthly cashback cap | Rs. 5,000 | Rs. 1,500 on Swiggy | No overall cap stated |
| Card network | Visa | Mastercard | Visa |
SBI Cashback Credit Card: The Broadest Net
The SBI Cashback Card is the only card in this comparison that does not require you to shop online. Five percent cashback credit card returns on every eligible online transaction regardless of the merchant, whether that is Myntra, Nykaa, BookMyShow, Zomato, Tata Cliq, or a brand website you have never heard of. No partner exclusions, no portal routing, and no voucher purchases required.
That breadth is genuinely rare. Most cashback credit cards at this fee level restrict their top rate to a handful of partner platforms. The SBI card applies it across the board, meaning every online transaction you make, not just those that fall on a partner list, earns at the same rate.
The monthly cap of Rs. 5,000 is the most generous in this comparison by a significant margin. To hit that cap, you would need Rs. 1 lakh in eligible online spend in a single month, a realistic ceiling only for heavy online shoppers. Most users will never touch it.
The annual fee of Rs. 999 plus GST disappears entirely if your annual card spend crosses Rs. 2 lakh, roughly Rs. 16,700 per month in total spending across online and offline categories. You can always check full exclusions list and waiver conditions on SBI Card’s official cashback page.
The gap: offline spending at 1 percent is unremarkable, and categories like fuel, rent, insurance, EMIs, and utility payments are excluded from the 5 percent rate. If a significant portion of your online spending falls into those categories, your effective return drops considerably relative to the headline rate.
HDFC Swiggy BLCK Credit Card: The Deepest Specialist
The HDFC Swiggy BLCK delivers the highest single-category cashback rate in this comparison at 10 percent on Swiggy food delivery, Instamart grocery orders, and Swiggy Dining restaurant bookings, capped at Rs. 1,500 per month. To earn the full Rs. 1,500 cashback, you need to spend Rs. 15,000 per month within the Swiggy ecosystem.
For a household that genuinely routes most of its food, grocery, and dining spend through Swiggy, this is a powerful card. Ten percent is difficult to beat on any category from any Indian cashback credit card at this fee level, and the Swiggy ecosystem is broad enough that groceries through Instamart, restaurant dining through Swiggy Dining, and daily food delivery all count toward the same cap.
The card also maintains 5 percent cashback on eligible online shopping outside Swiggy, capped at Rs. 1,500 per month, giving it a secondary earning layer that is competitive with the SBI card on overlapping categories.
The limitation is the narrowness of the 10 percent tier. The moment you step outside Swiggy’s ecosystem, the card becomes a 5 percent online card, identical to the SBI card on that dimension but with a lower cap and a higher annual fee before waiver. The full benefit structure and merchant exclusions are on HDFC Bank’s official Swiggy page and worth reading before deciding between ORNGE and BLCK.
The annual fee of Rs. 1,000 plus GST has no spend-based waiver. You pay it every year regardless of how much you spend, which means the card needs to earn at least Rs. 1,180 more in cashback per year than a lifetime-free alternative justifies holding it.
Amazon Pay ICICI Credit Card: The Lifetime Free Champion
The Amazon Pay ICICI card is the only lifetime free card in this comparison, which changes the value calculation fundamentally. You are not paying Rs. 999 or Rs. 1,180 per year to hold it. Every rupee of cashback it earns is net positive from day one.
For Amazon Prime members, the card returns 5 percent on all Amazon.in purchases including Fresh, Now, and Pantry, directly credited as Amazon Pay balance at the end of each transaction. For non-Prime members, that rate drops to 3 percent. On partner brands including Swiggy, Uber, Myntra, BookMyShow, and several others, the cashback rate is 2 percent.
The absence of a monthly cap is the card’s most distinctive structural feature. The SBI card caps at Rs. 5,000 per month. The Swiggy BLCK caps at Rs. 1,500 on its top tier. The Amazon Pay ICICI card does not publicise an overall monthly cashback ceiling, which means high-volume Amazon spenders are not penalised for crossing an arbitrary threshold mid-month. Current cashback rates and Prime membership conditions are confirmed on ICICI Bank’s Amazon Pay card page.
The cashback lands as Amazon Pay balance, not as a statement credit, which means you can only deploy it within Amazon’s ecosystem. For someone who spends heavily on Amazon already, that is not a restriction. For someone who wants flexible cashback they can use anywhere, it is a meaningful limitation.
The Spending Pattern That Determines Your Card
This comparison does not have a single winner. It has three winners for three different spending profiles, and the wrong card for your profile costs you real money every year compared to the right one.
Choose the SBI Cashback Card if your online spending is spread across many platforms and you do not want to think about which merchant qualifies for which rate. Five percent on everything online with a Rs. 5,000 monthly cap and a fee that disappears at Rs. 2 lakh annual spend is the simplest and most consistent proposition in this group. It is the best cashback credit card choice for anyone who values breadth over depth.
Choose the HDFC Swiggy BLCK if Swiggy is genuinely your primary food, grocery, and dining channel and your monthly spend within the Swiggy ecosystem consistently crosses Rs. 2,000. Below that threshold the annual fee eats into the advantage over a lifetime free card. Above Rs. 5,000 in monthly Swiggy spend, the 10 percent rate delivers cashback that neither of the other two cards can match on that specific category.
Choose the Amazon Pay ICICI Card if you are an Amazon Prime member whose biggest monthly online spending consistently happens on Amazon.in. Zero annual fee, 5 percent on Amazon with no cap ceiling makes it structurally the best credit card rewards proposition for heavy Amazon users who want guaranteed returns without paying to hold the card.
The cleanest wallet for many urban households is actually a combination: the Amazon Pay ICICI card as a free base layer for Amazon spending, paired with either the SBI card for broader online coverage or the Swiggy BLCK for Swiggy-heavy households. Holding two cashback credit cards with complementary category strengths consistently outperforms any single card across a full year of spending. Every current alternative worth considering sits on the cashback credit cards comparison page alongside these three.
Frequently Asked Questions
SBI Cashback Card at 5 percent on every online merchant with a Rs. 5,000 monthly cap is the broadest option. Amazon Pay ICICI wins for Amazon-heavy spenders with no annual fee and no stated monthly cap.
At 3 percent on Amazon instead of 5 percent, it is still worth holding because the card is lifetime free. But the value gap versus the SBI card narrows enough that non-Prime members should weigh whether the SBI card’s broader 5 percent coverage serves them better.
Yes. Any eligible online transaction earns 5 percent regardless of the merchant, which includes food delivery apps. The SBI card is effectively a stronger Zomato card than the Swiggy BLCK for anyone splitting food orders across multiple platforms.
It applies regardless of how much you spend. There is no waiver threshold on the BLCK card. If your Swiggy spend falls below Rs. 2,000 per month consistently, the card costs more in fees than the extra cashback it earns over the free ORNGE variant.
Yes and it is one of the most efficient free-and-paid cashback combinations available in India. Amazon Pay ICICI handles all Amazon spend at zero cost, and SBI Cashback handles every other online platform at 5 percent.