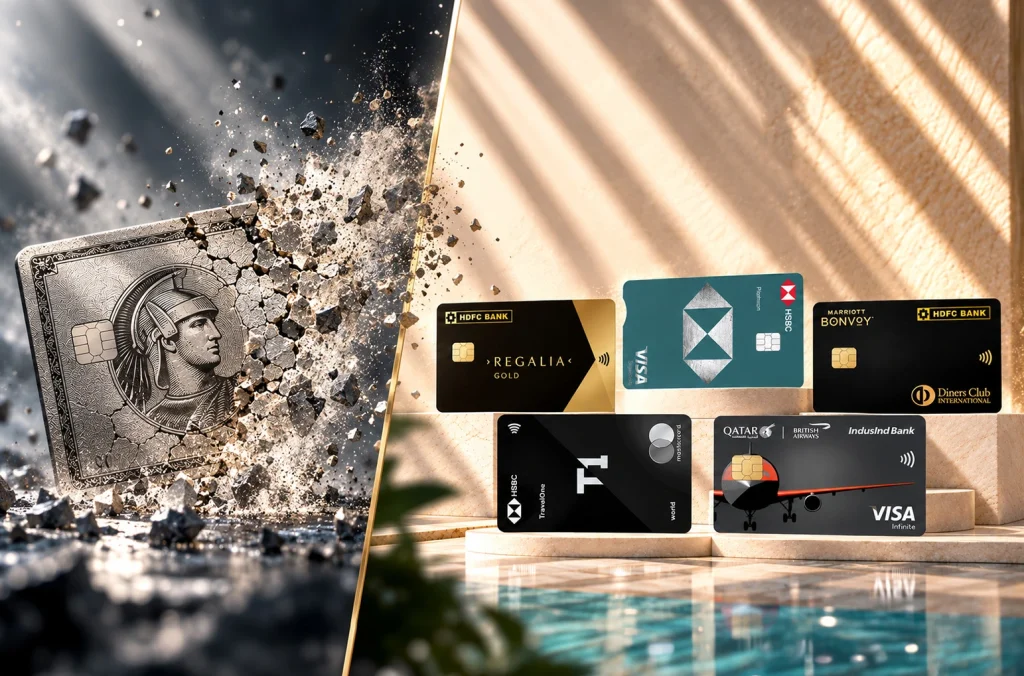
The Amex Platinum Travel Card was one of those rare credit cards that genuinely over-delivered for years. Spend Rs. 4 lakh annually, collect 40,000 milestone MR points, grab a Rs. 10,000 Taj vouchers, and walk away feeling like the system was rigged in your favour. Then 2026 happened. The Rs. 1.9 lakh milestone bonus vanished. The Rs. 7 lakh milestone’s 22,500 MR points got replaced with a Rs. 20,000 Taj vouchers. And thousands of cardholders were left asking: what now?
There is no perfect replacement. The Amex Platinum Travel Card at its peak was an anomaly, and anomalies do not have exact substitutes. But there are five cards across different price points that each solve a specific piece of what the Plat Travel used to solve.
The Truth About the Devaluation
At Rs. 4 lakh annual spend today, you get 10,000 MR points, a Rs. 5,000 annual fee, and nothing else. No second milestone. No bonus tier. The math no longer works for moderate spenders. Offers have always been limited time only. The era of extracting 30 to 40 percent effective return from a mid-tier card is over for this particular product. What the market currently offers as alternatives is what matters now.
Ground Zero: The Free Card That Still Transfers to Miles
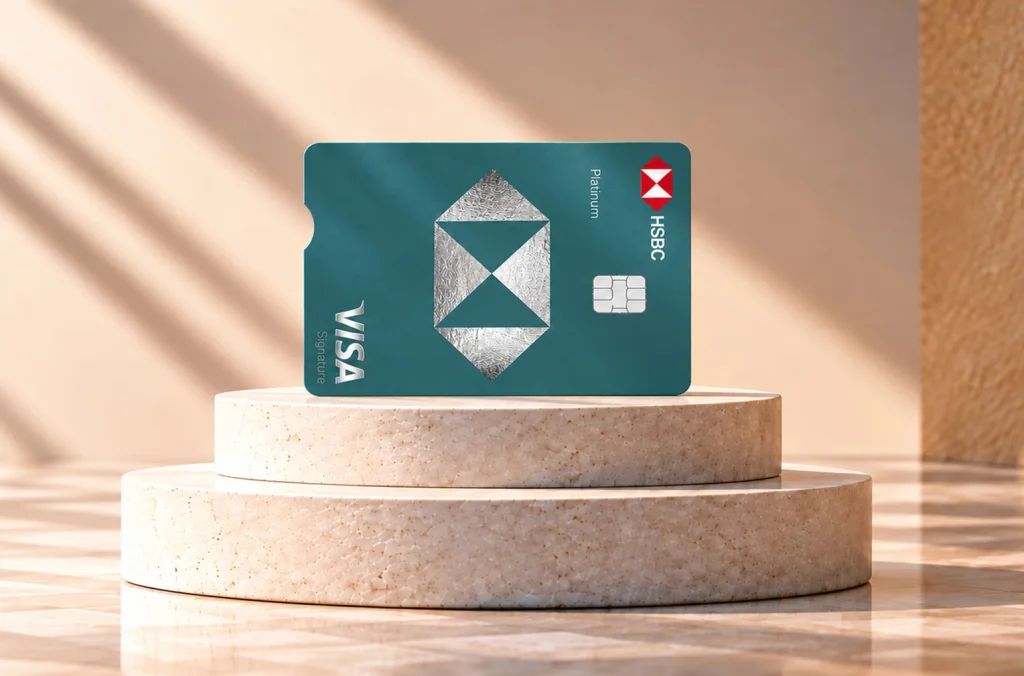
For anyone wanting to enter the points and miles world without a joining fee, the HSBC Platinum Credit Cards is the most underrated starting point in India. Lifetime free and transferable to the same airline partner ecosystem as HSBC TravelOne, including KrisFlyer, Japan Airlines, and British Airways Avios. The reward rate is modest but the transfer capability is what matters. A free card connecting to meaningful airline partners beats a free cashback card that goes nowhere every single time.
If you want a no-brainer alternative with zero forex markup and UPI earning instead, the Scapia Credit Card is a strong zero-fee companion with unlimited lounge access on Rs. 20,000 monthly spend.
Level One: The Core Card That Builds an Ecosystem
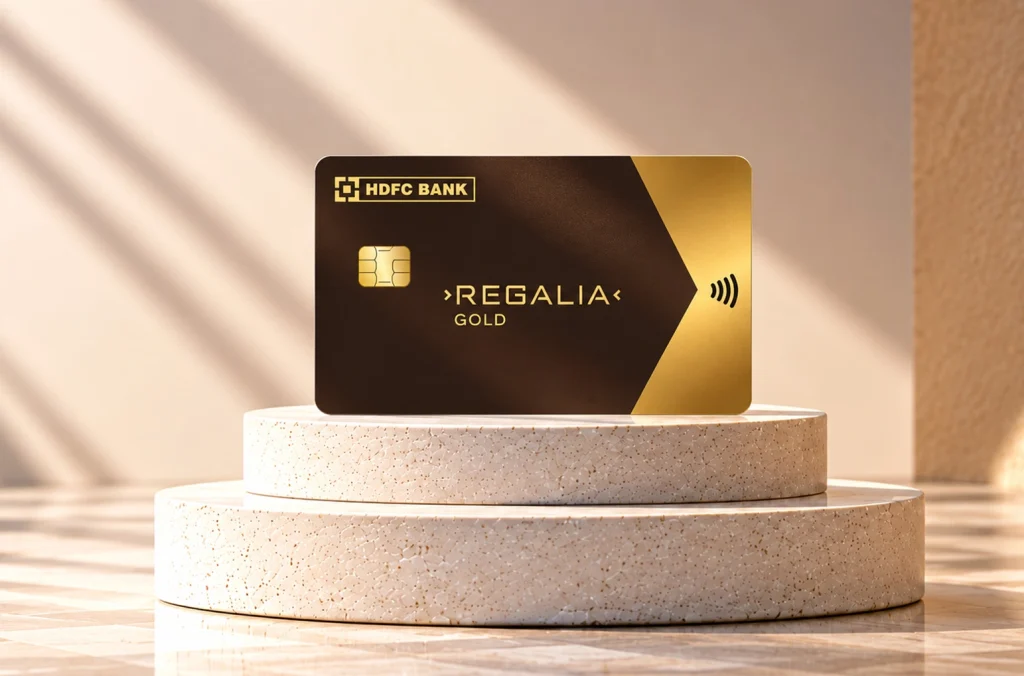
The HDFC Regalia Gold is consistently underrated despite being widely held. The 1.25 percent base rate looks weak until SmartBuy enters the picture. At 5x on SmartBuy hotel and flight bookings, effective returns hit 12.5 percent and 7.5 percent respectively. If even 30 to 40 percent of your annual spend goes through SmartBuy categories, the blended return outpaces the devalued Amex Platinum Travel Card comfortably.
It runs on Visa and Mastercard, solving the acceptability gap Amex cardholders frequently hit. Accor is a transfer partner at 2:1, and the card upgrades structurally toward Diners Club Black and Infinia as spend grows. At Rs. 2,500 annual fee with Rs. 1.5 lakh monthly salary eligibility, this is the anchor card at this price point.
Level Two: The Marriott Entry Point
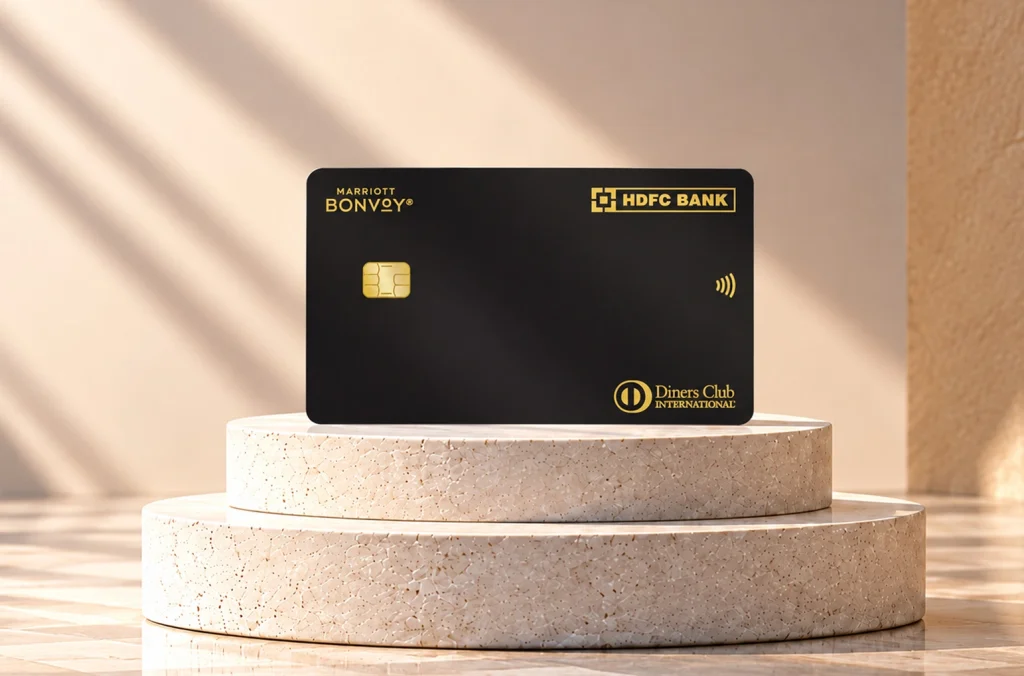
At Rs. 3,540 all-in, the Marriott Bonvoy HDFC Credit Card delivers a 15,000-point Free Night Award as a welcome benefit. A mid-tier Indian Marriott property costing 15,000 points per night is worth Rs. 12,000 to Rs. 25,000 in cash. The joining fee pays for itself before you have made a single transaction.
Three more Free Night Awards unlock at Rs. 6 lakh, Rs. 9 lakh, and Rs. 15 lakh in annual spend. Marriott Bonvoy points transfer to over 40 airline partners at a 3:1 ratio with a 5,000-mile bonus for every 60,000 points transferred, giving the currency far more versatility than the Taj voucher the Plat Travel now delivers. The full transfer partner list is on Marriott Bonvoy’s official loyalty programme for verification before applying.
Level Three: The Travel Specialist
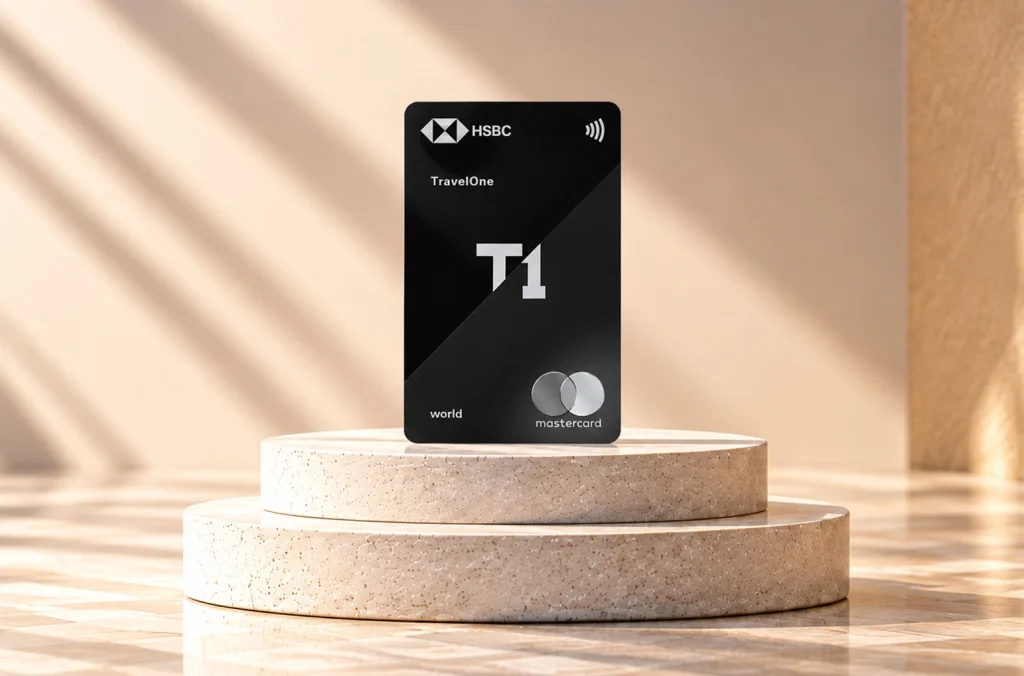
The HSBC TravelOne Credit Card is the most direct Amex Platinum alternative for travel-focused spenders. The 2 percent base rate doubles in value when converted to Accor Live Limitless at 1:1, delivering approximately Rs. 4 per point. Book through Hopper via TravelOne and earn rates jump to 4x to 8x. Even at a 70 to 30 non-travel to travel spend ratio, the blended return approaches 5 to 6 percent annually, which is exactly where the Plat Travel used to sit before the Amex Platinum Travel Card devaluation.
Transfer partners include KrisFlyer, Japan Airlines Mileage Bank, British Airways Avios, Finnair Plus, and Accor. The Rs. 5,000 annual fee is the price of entry. Full benefit details are on HSBC India’s official TravelOne listing.
Level Four: The Tax and Utility Spender’s Card
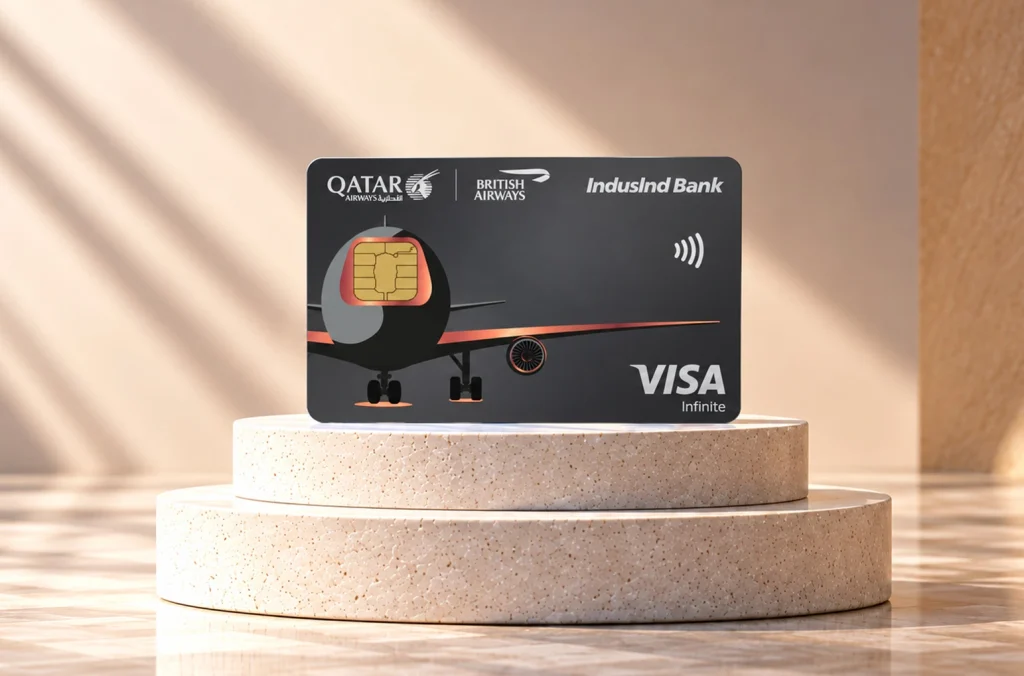
Most premium best travel credit cards India exclude tax payments and government transactions entirely. The IndusInd Bank Avios Visa Infinite Credit Card earns on these categories at a reduced rate, which is the single most meaningful differentiator on this list for high-earning professionals with significant advance tax outflows.
The welcome benefit is 10,000 Qatar Avios miles worth Rs. 11,000 to Rs. 15,000 in real redemption value, more than offsetting the Rs. 10,000 plus GST joining fee. At Rs. 16 lakh annual spend, the total effective earn rate approaches 3.75 percent before the welcome bonus.
Avios transfers across British Airways, Iberia, Finnair, and several other oneworld alliance carriers, making it the only co-branded Avios card in India. Current terms are on IndusInd Bank’s official Avios card listing.
Which Card Is Actually for You
The framework is simple: how much can you spend annually and what is your biggest spend category?
Rs. 7 lakh annually with a travel focus: HSBC TravelOne at Rs. 5,000. Rs. 3 lakh to Rs. 6 lakh across varied categories: HDFC Regalia Gold at Rs. 2,500. Rs. 6 lakh to Rs. 15 lakh with significant hotel stays: Marriott Bonvoy HDFC at Rs. 3,000. Rs. 16 lakh or above with tax and utility spends: IndusInd Avios at Rs. 10,000. Zero fee starting point: HSBC Platinum, lifetime free.
None of these replicate the old Plat Travel milestone structure. But each delivers better returns than the devalued Amex Platinum alternative on the right spending profile. The cards that win today are the ones matched to a category, not the ones expected to handle everything at an exceptional rate.
Frequently Asked Questions
No single card replaces it perfectly. HSBC TravelOne is closest for travel-focused spenders above Rs. 5 lakh annual spend. HDFC Regalia Gold works better for broad everyday spending with SmartBuy routing.
For most spending profiles above Rs. 5 lakh annually, yes. TravelOne’s Accor transfer value combined with Hopper multipliers outperforms the devalued Plat Travel on the same spend pattern.
The IndusInd Bank Avios Visa Infinite is the only premium travel card in India earning on tax and government payments, making it the most relevant replacement for high earners with significant advance tax outflows.
Not immediately. Wait to see if Amex offers a retention incentive at renewal. Below Rs. 7 lakh annual spend, the fee-to-return ratio no longer justifies keeping it as a primary card.
HSBC Platinum for anyone wanting to enter the miles transfer ecosystem at zero cost. Scapia for anyone wanting a no-brainer everyday card with UPI earning and zero forex markup without transfer partner complexity.